
The Loan Officer Employment Plan FORM 3-10 is a fundamental document because it outlines what the MLO must do to earn the commission. BUT NEVER put the actual compensation amount IN THE PLAN. That means you can't change it without executing a new agreement. Always keep the compensation plan separate. For comp, you should have the Employment Plan plus:
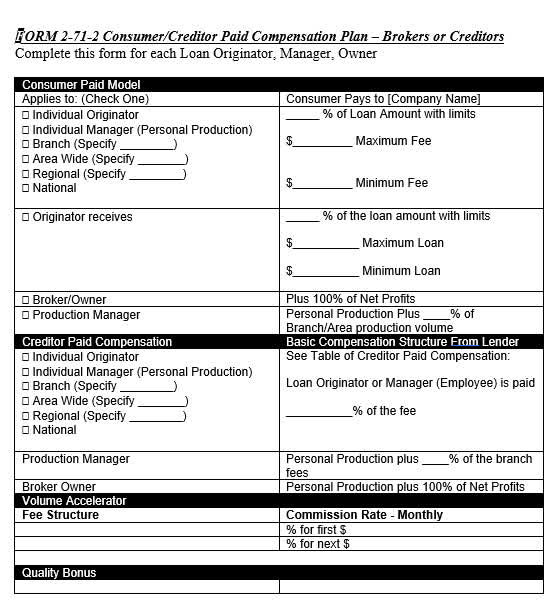
1.) a borrower-paid and lender-paid FORM 2-71-20, and, if there are volume kickers,
a.) You can use the Volume Accelerator in FORM 2-71-20 or use the sample volume-based sample.
2.) Finally, you need to have your own company's list of all lender-paid comp (for brokers) plans, FORM 2-71-22
Hybrid Broker/Correspondent Business Model
Mortgage loan originators can price and lock lender-paid loans because the pricing arrangement is fixed, and the commission amount follows the fixed lender-paid schedule.
Borrower-Paid and Correspondent Comp Models MUST be Loan Amount based
Even if the loan is still brokered, or a banked/correspondent loan, you MUST use a loan amount-based fixed commission rate.
You must control pricing distribution to MLOs.
Secondary Marketing/Management must include the gross price so that the company profit margin at lock-in is not evident to the mortgage loan originator.