
UPDATE 10-21-2026: IDFPR is citing companies for NOT retaining their own broker agreements
General Examination Support
Here is a matrix of frequently requested policies and their locations.
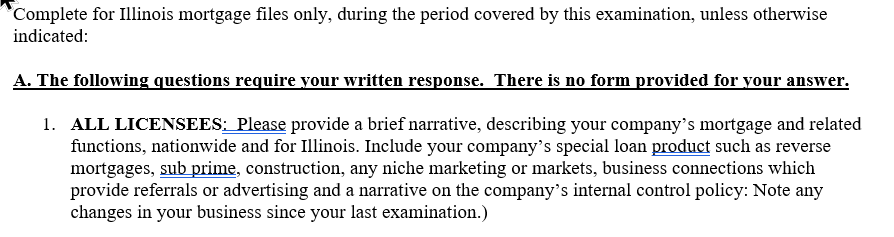
As mentioned, Illinois examiners are expecting you to write, in your own words, a narrative of your mortgage functions. You can use the "Regulatory Business Plan" we provide as a model. This is typically known as a business plan - but if they ask for the Control Policy - they are referring to your "1-A Quality Control Plan", so when they ask for a narrative of the control policy, we suggest using the introduction of the QC plan and an extract of the table of contents.
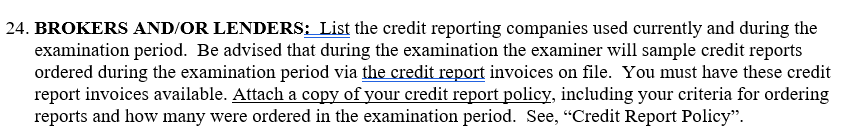
Your Credit Score Disclosure comes from your credit bureau, for the most part, although some lenders do provide their own. Pull a copy of this from one of your loan files.
Safeguarding is your information security policy, Sections 2-90 - 2-92. The Disposition Policy is included in the 2-90 IT Security Plan.
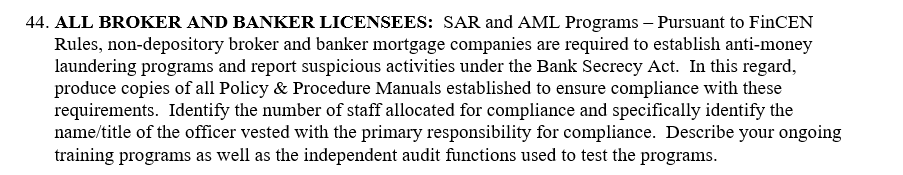
44. Your BSA/AML SAR (Suspicious Activity Reporting) Plan extends, and is included in, your 1-A Quality Control Plan > See Section 1-70 BSA/AML Plan. Within this, you describe your minimum required training (you should take the courses listed or provide proof that you have taken AML training - always retain certificates and training materials for review). At the end of the AML plan, you will see the section on independent audit. You must conduct periodic independent reviews. We give you a form to do this. If you have an independent function, you can use that, but if you need an independent review, we can conduct one here:
https://www.mortgagemanuals.com/annual-amlbsa-audit.html
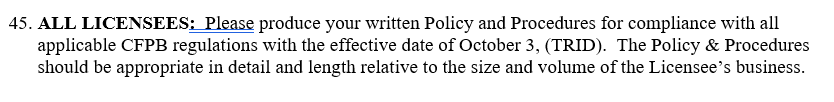
45. As a broker, most lenders provide the LE/CD. You can say that, but you should also provide the 2-0 Compliance > 2-14 - 2-15 TRID Policies and Procedures.
It's a common misconception that GFE/HUD-1 TIL is no longer in existence, but if you do HELOCS, Reverse/HECM or LOT loans, that's what you use. You also must retain proof that you provide and retain copies of the Know Before You Owe (Settlement Costs) handbook and all copies of the various disclosures required.
If you want us to help pull all this together for you, we can do it under our audit prep service.
https://www.mortgagemanuals.com/state-audit-prep-package.html